Key Takeaways
- Bitcoin slipped to about $80,698 on Oct. 24, below its 50-day average near $81,784.
- Coinglass-tracked liquidations hit $495.74M in 24 hours, with $318M coming from long positions.
- The Oct. 28 FOMC decision and Oct. 29 PCE print are the next tests for buyers.
The Line That Broke
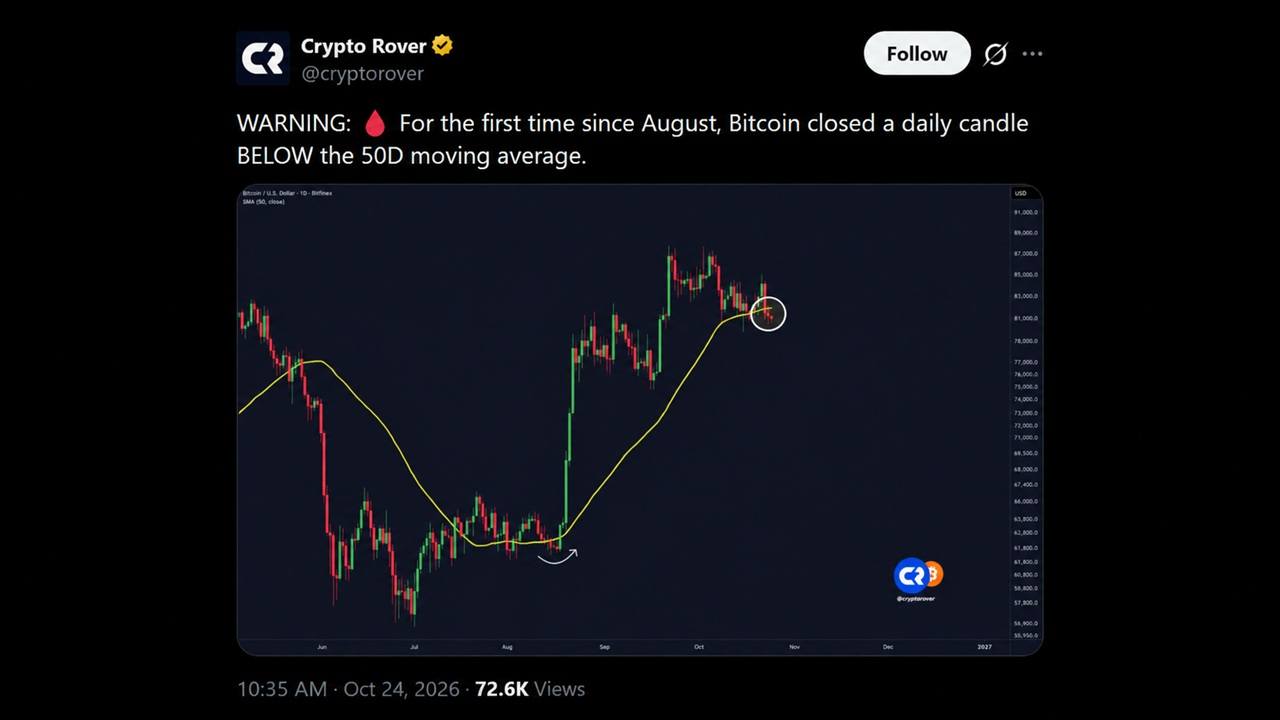
For roughly two months, bitcoin’s 50-day moving average (MA) acted like a floor where every dip toward it got bought. That status quo, however, changed on Friday, when bitcoin closed a daily candle below the indicator for the first time since August.
As of Saturday morning, bitcoin is trading around $80,800, down 1% on the day. Coingecko’s daily closes put the 50-day average near $81,784, which means the line that used to catch the market is now sitting about $1,000 overhead.
Traders tend to treat a reclaimed 50-day average as a sign of strength and a lost one as a warning. In fact, Bitcoin.com News flagged the setup a day earlier, when BTC’s price was stuck near $81K as oil continued to climb.
What Lit The Fuse
The trigger was seemingly geopolitical, given that on Friday, President Donald Trump said “we may do another operation against Iran.” Subsequently, other outlets relayed this phrasing, saying that Washington could launch a “little Epic Fury,” a reference to Operation Epic Fury, the U.S. campaign against Iran that began in late February.
The comments landed on markets that were already on edge, resulting in the Dow falling 652 points on Friday as rising oil prices weighed on Wall Street, and nearly three out of four S&P 500 stocks closed in the red. Analysts estimated that $140 billion was wiped from the total crypto market cap over the week as crude pushed toward $120 a barrel.
The Flush
Leverage also had its part to play as data shared by Whale Insider showed $318 million in longs liquidated across crypto in 24 hours. A broader Coinglass snapshot counted 175,527 traders liquidated for a combined $495.74 million, with the single largest order, a $4.77 million ETH position, blowing up on Binance.
Spot investors were already heading for the exits and on Thursday, U.S. spot bitcoin exchange-traded funds (ETFs) logged their biggest outflow since June, a $635 million exit led by Blackrock and Fidelity. Whale Insider reported a further $137.94 million in sales by ETF issuers on Friday.
The Calendar Now in Charge
Analyst Benjamin Cowen laid out a step-by-step path for a deeper slide. It starts with a weekly close below $83,000, moves through a Federal Reserve meeting on Oct. 28 and a hot personal consumption expenditures (PCE) inflation reading on Oct. 29, and ends with oil spiking toward $120. He said the scenario is void if bitcoin “gets and holds back above $83k.”
Cowen also noted that bitcoin keeps spending time below its May high, adding that the “burden of proof is starting to shift” with the Nasdaq down 8%. Other commentators warned that the next 10 days could be volatile, with Israel’s election on Oct. 27, the Federal Open Market Committee (FOMC) decision on Oct. 28 and Big Tech earnings stacked on top.
Not everyone is bearish, however, and some traders said they are adding to existing longs in what they referred to as a buy zone. Momentum gauges have cooled, though, and the Bitcoin Bull Score Index recently dropped from 80 to 60.